Projects
Signature-based optimal execution
Signature methods · Optimal execution · Python
This project studies optimal trade execution with trading speeds expressed as linear functionals of the observed price path’s signature. A custom symbolic algebra layer uses shuffle products and tensor concatenation to assemble quadratic execution objectives.
Validation includes a Brownian optimal-inventory benchmark, a liquidation problem with a known closed form, and geometric Brownian motion experiments. The implementation checks objective curvature before accepting a stationary point as an optimum.
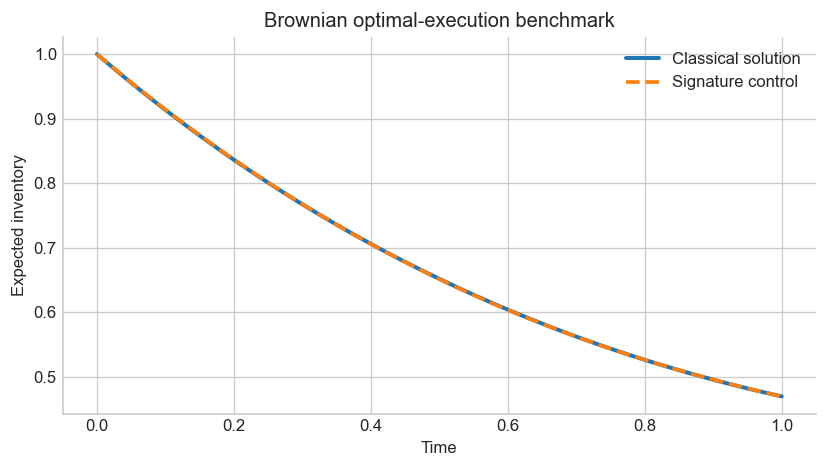
Brownian benchmark: expected inventory from the signature-based control compared with the classical solution for the notebook’s example.
Kalman filtering with signatures
Stochastic filtering · Signature methods · Jupyter Notebook
This project numerically reproduces the recovery of the continuous-time Kalman–Bucy filter using linear signature regression. The repository contains the implementation and notebooks for exploring the method.
Polymarket–Kalshi arbitrage research
Prediction markets · ATP tennis · Python
This project collects ATP tennis data and investigates cross-exchange arbitrage using Polymarket and Kalshi.